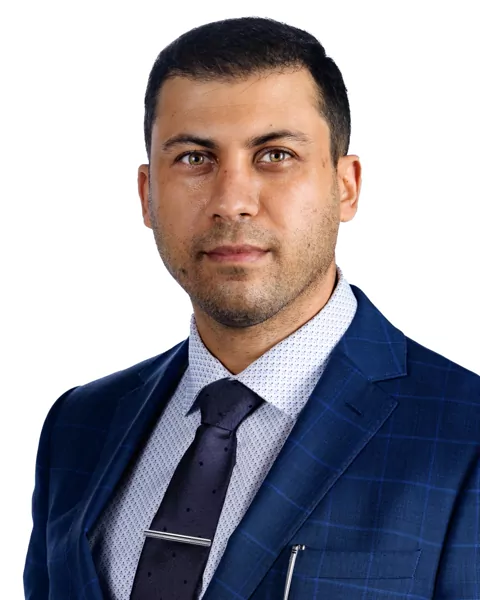
Ramin Hallaji-Dezfouli
Reverse mortgage specialist, British Columbia & Alberta
About Ramin →Check my licence yourself:

Recognition
For homeowners 55+ in BC & Alberta
The house did its job.
Let it fund the next chapter.
A reverse mortgage turns home equity into tax-free money, with no required monthly payments, while you stay home and stay the owner. We show you the honest year-by-year math first, so the decision is truly yours.
What stays true, always
- You stay in your home and on title. Nobody moves, nothing is sold.
- No required monthly payments. Pay the interest if you want to, or don't.
- The money is tax-free: it's loan proceeds, not income.
- You can never owe more than the home is worth: the no-negative-equity guarantee.
How it works with us
Our version of selling a reverse mortgage is refusing to.
It's a good product with a real cost that compounds quietly. So we don't pitch. We model, compare, and recommend in writing. Reverse when it's right, the cheaper alternative when it isn't. That's why clients call Ramin Hallaji the Reverse Mortgage Guru.
1. A real conversation
Your age, the home, and what the money is for. Family welcome: we think the best reverse decisions are made out loud, together.
2. The honest math
We model the balance year by year, compare the HELOC you might qualify for instead, and put our recommendation in writing. If a cheaper option wins, we say so.
3. Funding, protected
Independent legal advice is standard, you stay the owner, and the no-negative-equity guarantee means you never owe more than the home is worth.
What it solves
Equity working, payments gone.
Retirement income top-up
Monthly advances or a lump sum from the home, tax-free, with no required payments.
See what it pays →Stay in the home you love
The whole point: age in place without selling, downsizing, or taking on a payment.
A retirement without mortgage payments
An existing mortgage or consumer debt cleared, so the pension stops servicing payments.
Buying the next home
Right-sizing to a new home using a reverse mortgage on the purchase itself.
Early inheritance & family help
Helping kids with down payments now, from equity, without touching investments.
Under 55? There's a path
Fraction's no-payment mortgage pauses payments for up to five years, at any age.
Case study
At 78, still paying a bank mortgage
A Vancouver homeowner living on a pension of about $40,000 a year still owed about $290,000 to a bank, plus $35,000 of unsecured debt and an $81,000 business loan. A reverse mortgage of about $430,000, roughly 47% of the home's value, repaid all three, so no monthly mortgage payment is required and the homeowner stays in the home. Interest builds on the balance over time, and the homeowner still has to keep the property taxes and home insurance current, and keep the home as their residence.
Read the case study on mortgageguru.ca →The centerpiece
Will the house outrun the loan? See it in 60 seconds.
Our projection tool shows the race between your home's value and the compounding balance, year by year to age 95, including what your estate keeps, the probate math by province, and what changes if you choose to pay the interest monthly.
Bring the family. Seriously.
Adult children usually have the most questions: about the inheritance, the guarantee, and the alternatives. We welcome them into every conversation, and this whole site is written for them too.
Read the honest-math page →Free live webinars
Prefer to learn before you talk to anyone? Join one of our live educational sessions on reverse mortgages for Canadian homeowners 55+. Questions encouraged, no obligation ever.
See upcoming webinars ↗Straight answers
The three questions everyone asks first.
What is a reverse mortgage and who qualifies?
A reverse mortgage lets homeowners 55+ access tax-free equity with no required monthly payments, commonly up to about 55% of the home's value, sometimes higher under certain programs for older homeowners. Qualifying is based on the home and your age, not income or credit. There's no stress test.
When does it get repaid?
When the home is sold or the last borrower moves out. There's no fixed term and no required payments along the way. A no-negative-equity guarantee applies: neither you nor your estate ever owes more than the home's fair market value. The guarantee is the lender's, not ours (CHIP, Equitable Bank, Bloom and Home Trust each carry one), it holds as long as the mortgage's obligations are kept, and the product terms govern.
What's the catch?
Compounding. With no payments, interest accrues onto the balance, so the debt grows while you stay. That's the product working as designed, not a trick. The real question is whether the equity you're using buys something worth more to you than the inheritance it reduces. We put the year-by-year math in front of you before any decision.
Is Ramin a certified reverse mortgage consultant?
Yes. In October 2026 Ramin completed all eleven modules of the Certified Canadian Reverse Mortgage Consultant (CCRMC) program and passed its final exam with 90%. Ramin is on the program's public list of graduates, for British Columbia and Alberta. The designation sits on top of his mortgage broker licences in British Columbia and Alberta, which are what allow him to arrange your mortgage.
See your numbers before you decide anything.
Tell us your age, the home, and what the money is for. We'll show you the year-by-year math, the alternatives, and our honest recommendation, in writing, with your family welcome at the table.
In a hurry? Answer seven quick questions and Ramin calls you with your figure. About 3 minutes, no obligation.
Prefer to learn first? Join a free live webinar.